AZ Weekly Post
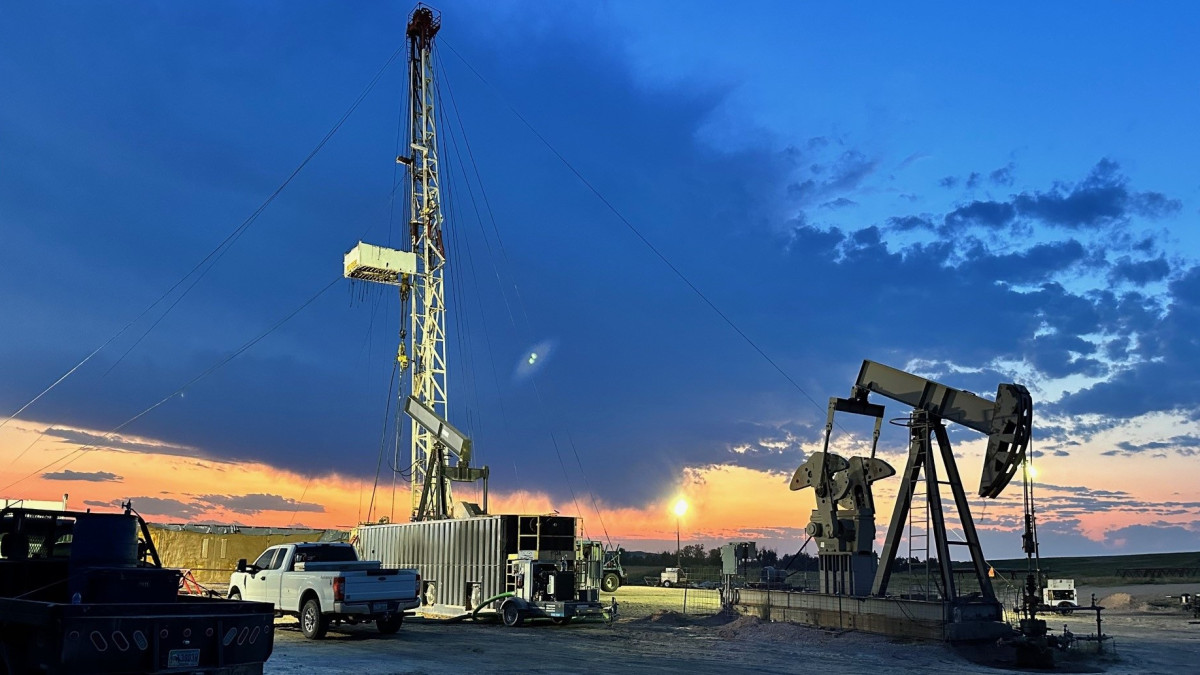
Baker Hughes (BKR) just signed a new Power Frame Agreement with Venture Global and GE Vernova, setting up as many as 16 behind the meter power islands to support LNG and potential data center projects. Baker Hughes has seen short term share price momentum cool a little, with the stock drifting over the past month but still posting an 18.16% year to date share price return and a 5 year total shareholder return of 153.55% that reflects a much stronger long term story. Fresh agreements across LNG, Venezuelan gas infrastructure and a wider oil and gas technology partnership with New Stratus Energy have arrived just as the share price ticked up 2.39% in the last day, a move that hints at investors reassessing both growth options and risk around the new Power Frame Agreement at a US$55.70 price level.
Scan peers riding similar LNG and power trends by jumping across to our hand picked 41 power grid technology and infrastructure stocks as you weigh Baker Hughes against other infrastructure plays tied to energy and data growth. Baker Hughes now trades at US$55.70, and sits between a 27.8% gap to analyst targets and a much wider implied discount to some intrinsic estimates. Which reference point best reflects fair value today?
Most Popular Narrative: 23% Undervalued Baker Hughes is framed as undervalued in the most followed narrative, which pegs fair value at $72.30 against the recent $55.70 close and emphasizes orders and mix shift into higher margin areas. The company is building on its momentum in large technology driven orders, with Industrial & Energy Technology securing US$7.1b of orders in Q2 2026 and a 2.2x book to bill. This supports multi year revenue visibility and the potential for steadier earnings from a larger backlog.
See why 37 investors see Baker Hughes as 23% undervalued . Result: Fair Value of $72.30 (UNDERVALUED) Still, the Baker Hughes story can break if Chart integration drags, cost synergies slip, or higher interest and leverage keep free cash flow conversion under pressure. Find out about the key risks to this Baker Hughes narrative .
Next Steps Whether you are optimistic or cautious about Baker Hughes after all of this, the real edge comes from running the numbers yourself and pressure testing the thesis while sentiment is still shifting, then weighing those positives against the 5 key rewards . Looking for more Baker Hughes style investment ideas? If you stop with Baker Hughes, you miss the bigger opportunity set.
Use the Simply Wall Street Screener to quickly surface focused ideas across quality, income and upside. Target resilient businesses that aim to protect your downside while still leaving room for upside by scanning our 32 resilient stocks with low risk scores . Hunt for high quality companies that appear out of favour on price by working through the 33 high quality undervalued stocks .
Build a cash flow focused watchlist by leaning on the 8 dividend fortresses for ideas with income potential on top of any share price return. This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned. Valuation is complex, but we're here to simplify it. Discover if Baker Hughes might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free Analysis Have feedback on this article? Concerned about the content? Get in touch with us directly.
Alternatively, email editorial-team@simplywallst.com
Source: Simply Wall Street